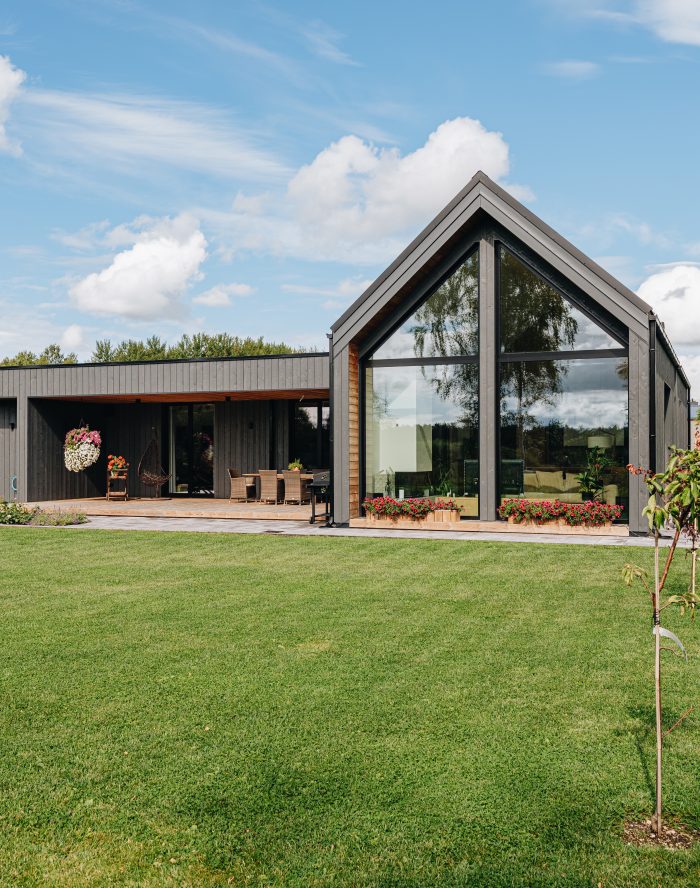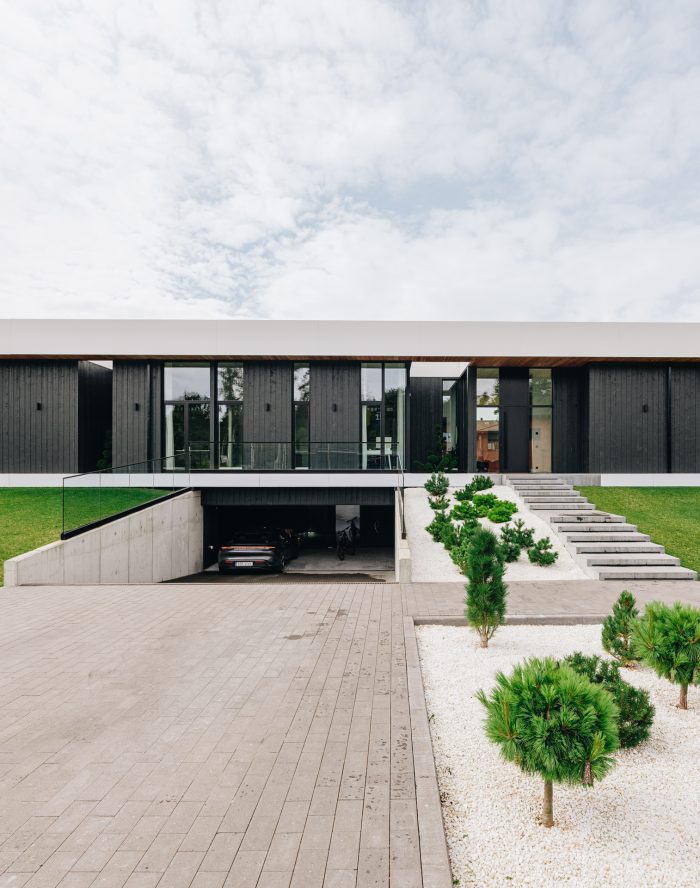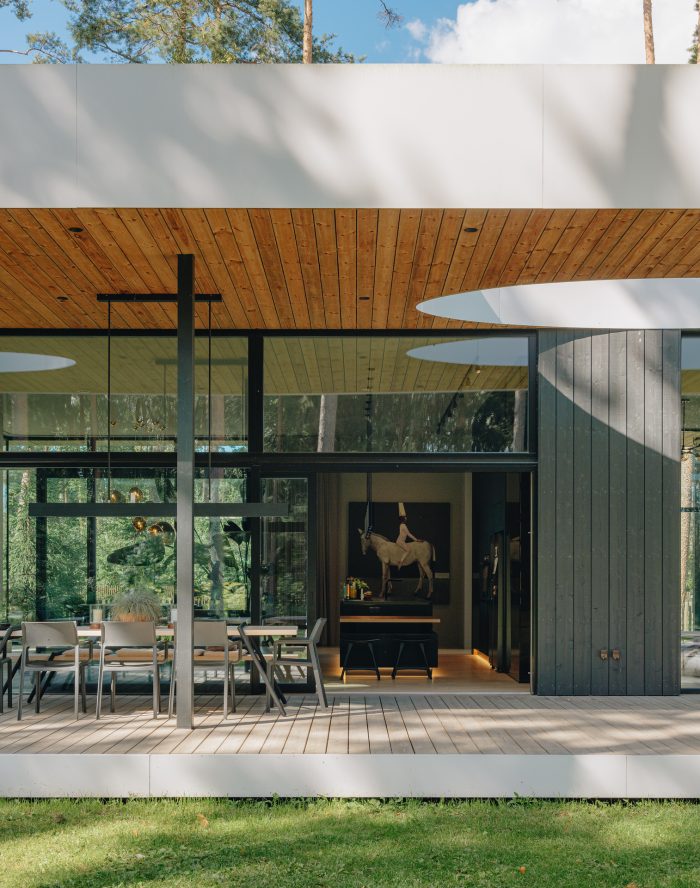



Building a house with a loan is for most families the only way to get their own home, but a construction loan works differently from the home loan you take on a finished flat. The bank finances a process whose collateral is still going up, so it asks for documents a buyer of a finished home never has to present.
Below are the seven things banks usually ask for when financing a factory-built house, and which of them we prepare. This is not financial advice: terms and interest depend on the bank and the client, and independent consumer information is available in Estonian from Minuraha.
How a construction loan differs from an ordinary home loan
With a home loan on a finished property the money is paid out at once and the property bought is the collateral. With a construction loan the collateral is a plot and a half-built house, so the bank releases the money in stages and checks that it goes into the work.
What matters to it is that the project is financed to the end: plot, construction, connections, finishing and a reserve. An incomplete budget is the commonest reason a decision drags on; what belongs in it is in our article on building a house from scratch.
1. The plot and its documents
The first question is the plot: whether it exists, is free of loans, or is still to be bought. It is often part of the collateral and is valued together with the future house, and the bank checks the plan to see whether what the loan finances may be built there. The plot documents, the detailed plan or design conditions and the building register extract are the same ones our architect asks for.
2. The building design and the building permit
The bank wants the design the house will be built to, and usually the permit before construction-stage disbursements start. Without it the work is not allowed and the collateral cannot be valued.
Our architect prepares the design and applies for the permit. An individual design takes one to three months on average and the permit procedure two to three months in practice, so count on months of paperwork before the first machine reaches the site. The types of consent are in our article on the building permit in Estonia. The design can go to the bank while the permit is in process, so that the construction loan decision and the permit arrive together.
3. A fixed-price construction contract
The bank wants to know who builds, at what price and with what scope. A fixed-price turnkey contract from foundation to interior finishing is clearer than several separate contracts, because the total and the responsible party are known. About the builder, bring register data, references and guarantees.
As orientation before a design exists, our indicative figures are these: a good standard of interior finishing starts from 400 €/m² + VAT, with a lower rate per square metre on larger houses, and the electrical work inside the house from 26 000 € + VAT. A more precise offer follows a consultation, once the wishes for the house have been mapped. What our contract covers is in our article on the turnkey house price.
4. The budget and the own contribution
A construction loan rarely covers the whole sum: part comes from the client’s own contribution, whose share differs between banks. An existing plot or work already done may count towards it.
The budget has to contain every line, not just the house: plot, surveys, design, state fees, connections, construction, outdoor works, finishing materials, furnishings and a reserve. To sketch a rough total before the bank meeting, our piece on the house building cost calculator shows what a quick estimate leaves out, and why a budget built on a single price per square metre does not hold up.
5. The valuation
The bank asks for a valuer’s assessment of the market value of plot and future house, based on the design. The valuer weighs location, plan, size, build quality and increasingly the energy class. The valuation needs the design, the builder’s offer and a technical description, which we give the client – see our article on the energy class A house.
6. The payment schedule and stage-based disbursements
A construction loan is paid out in parts: the bank checks a completed stage against the builder’s certificate, photos or an inspection and releases the next part, so the payment schedule must follow stages that can be evidenced. Ours is agreed in the contract; the stages – foundation, shell erection, closing the envelope, services, interior finishing and handover – are described in our article on house construction stages, and the project manager issues a certificate for each one.
7. Insurance and guarantees
During the build the site is covered by CAR insurance; afterwards the bank usually requires the collateral home to be insured. The guarantees, 50 years on the structures and 2 years on construction work, show that the value of the collateral holds.
Construction takes about 22 weeks in our case, though interior finishing can extend that. A short build also shortens the months in which the family carries the old home and the loan interest at once.
State guarantee and an energy-efficient home
For certain groups, for example young families, a state loan guarantee has been offered in Estonia that reduces the need for own contribution. Its conditions change, so check them with the Estonian Business and Innovation Agency and with your bank, which may have better home loan terms for an energy-efficient house.
Building a house with a loan: in what order to talk to the bank
Start with a preliminary loan decision: on the basis of income and assets the bank says roughly how large a construction loan is possible. That number is the budget frame the architect fits the house into, so ask for it before you choose a model, not after.
Then come the formal application, the loan contract with the mortgage, the disbursements stage by stage, and finally insurance and the occupancy permit. All this takes longer than buying a finished home, so talk to the bank when you send the plot documents to us.
Summary
For the bank we put together a written offer with its scope, the design, the construction contract and the payment schedule; the loan decision is the bank’s and the terms are yours to negotiate. Send the plot documents through the contact page and we will prepare an offer the bank can assess.
Do banks finance the construction of a factory-built house?
Yes, banks finance factory-built houses too. The bank looks at the plot, the design, the building permit, the contract with the builder and the budget. A turnkey contract with a fixed scope and a short build time are rather an advantage for the bank.
Does the plot have to be free of loans?
Not necessarily. The plot is often itself collateral, and some banks also finance the purchase of the plot. Conditions differ between banks, so ask your bank before signing a contract with the builder.